 Hi, my name is Phillip Ferguson. I’m a Loan Officer with NEXA Lending LLC., offering personalized mortgage solutions, fast customized quotes, great rates and service with integrity.
Your roof estimate is due, tuition is coming up, or a renovation can no longer wait. When your home has built meaningful equity, the decision often comes down to a cash out refinance versus HELOC. Both can turn equity into usable funds, but they work very differently. The better choice is not automatically the one with the lowest advertised rate. It is the option that fits your current mortgage, how much cash you need, and how long you plan to keep the home.
Cash Out Refinance Versus HELOC: The Core Difference
A cash-out refinance replaces your existing first mortgage with a new, larger mortgage. The difference between the new loan amount and the payoff of your current mortgage is delivered to you as cash at closing. You leave closing with one mortgage payment, a new interest rate, and new loan terms.
A home equity line of credit, commonly called a HELOC, is a separate loan secured by your home. Your existing first mortgage stays in place. The HELOC is generally a revolving line of credit, meaning you can draw money as needed during an approved draw period, up to your available limit.
That distinction matters. A cash-out refinance resets the financing on your entire mortgage balance. A HELOC adds a second payment and gives you more flexibility to borrow only what you actually use. Neither option is automatically better. The right move depends heavily on the mortgage you already have.
When a Cash-Out Refinance Can Make Sense
A cash-out refinance is often worth a close look when you need a larger, one-time lump sum. Homeowners use it to fund a major renovation, consolidate high-interest debt, buy out an owner after a divorce, make a significant investment, or handle a large planned expense.
It can be especially appealing if your current first-mortgage rate is higher than what you can qualify for today. In that situation, you may improve the rate on your existing balance while pulling cash from your equity. You also have the simplicity of a single monthly mortgage payment.
Most cash-out refinances offer a fixed interest rate and predictable principal-and-interest payment when you choose a fixed-rate mortgage. That payment certainty can be valuable when you are borrowing a specific amount for a defined purpose. If the project costs $75,000, for example, you know exactly how much is available at closing instead of managing multiple HELOC draws.
There is a trade-off: you are refinancing every dollar of your current mortgage, not just the cash you need. If you have a very low first-mortgage rate, replacing it with a higher current-market rate may raise the cost of the balance you already owe. A lower rate on the cash portion does not necessarily make the total transaction a win.
Cash-out refinances also have closing costs, although options vary by lender and loan structure. The loan term matters, too. Extending a mortgage back to 30 years can lower the monthly payment but may increase total interest over time. A shorter term or extra principal payments may be more appropriate for borrowers focused on paying the home off sooner.
Loan limits and qualification still apply
Cash-out availability is based on more than an online home-value estimate. Lenders evaluate the property value, existing liens, loan-to-value ratio, credit profile, income, debts, occupancy, and loan program guidelines. A primary residence, second home, and investment property can have different requirements and maximum loan amounts.
For eligible veterans, a VA cash-out refinance may offer a strong option. FHA, conventional, jumbo, and other programs may also fit depending on the property and borrower profile. The best structure comes from comparing the full payment, costs, and long-term impact, not simply asking how much equity is available.
When a HELOC Can Be the Better Move
A HELOC can be a smart choice when your current first mortgage is too good to replace. If you locked in a low fixed rate years ago, keeping that loan intact may save you from refinancing a large balance at a higher rate.
HELOCs work well for expenses that happen over time rather than all at once. A homeowner renovating room by room may draw funds for the kitchen now, the bathroom later, and only pay interest on the amount currently borrowed. That can be more efficient than taking a full lump sum before every dollar is needed.
Many HELOCs have a draw period followed by a repayment period. During the draw period, some plans may allow interest-only payments. Once repayment begins, the payment can increase because you must repay both principal and interest over a shorter remaining period. Understand that future payment before signing, not after the draw period ends.
The other major consideration is the rate. HELOCs commonly have variable rates tied to an index plus a lender margin. Your payment can rise if market rates rise. Some HELOC products offer fixed-rate conversion options for a portion of the balance, but the terms vary. Ask how often the rate can adjust, whether there is a rate cap, and what the highest possible payment could look like.
A HELOC is not free money simply because the payment starts low. It is secured by your home. Borrow with a clear purpose, a realistic repayment plan, and room in the budget for potential rate changes.
Compare the Payment, Not Just the Rate
A cash-out refinance may advertise a lower rate than a HELOC because it is a first-lien mortgage. But comparing rates alone can lead to the wrong decision. The refinance rate applies to your entire new mortgage balance. The HELOC rate applies only to the amount you draw, while your existing first mortgage remains unchanged.
Consider a homeowner who owes $250,000 at a low fixed rate and needs $50,000 for a renovation. A cash-out refinance would create a new mortgage for the existing payoff plus the cash needed, subject to closing costs and program limits. A HELOC would leave the $250,000 mortgage in place and add a separate line for the renovation. Even if the HELOC rate is higher, the overall household financing cost may be lower because the low-rate first mortgage stays put.
Now consider a homeowner with a higher-rate first mortgage who needs $100,000 to consolidate expensive debt and complete major repairs. Refinancing the first mortgage and taking cash out could create a better overall payment structure, particularly if the borrower wants a stable, fixed payment. The numbers decide the answer.
When comparing scenarios, look at the new monthly payment, cash received, estimated closing costs, rate type, maximum possible HELOC payment, and break-even period. Also consider how long you expect to own the home. Paying refinance costs for a property you plan to sell soon may not make sense, while a HELOC may provide temporary flexibility.
Timing, Credit, and Access to Equity
A cash-out refinance is generally a full mortgage transaction. It involves underwriting, an appraisal or valuation review when required, title work, disclosures, and closing. It may take longer than opening a HELOC, although timing varies by lender, property, and documentation.
A HELOC can offer faster access after approval in some cases, but it still requires qualification and property review. Do not assume an existing bank relationship guarantees the best terms or fastest process. Credit score, debt-to-income ratio, documented income, property type, and available equity all affect the options.
Both loans can affect your credit profile. A refinance pays off and replaces an existing mortgage, while a HELOC adds a new credit line and payment obligation. Large draws on a HELOC can change your debt picture if you later apply for a purchase loan, auto loan, or investment-property financing. Build your next goal into the conversation before you borrow.
Questions to Answer Before Choosing
Start with the purpose of the money. Is it a one-time expense with a firm price tag, or a project that will unfold over months? Then look at your existing mortgage rate and remaining balance. A great first-mortgage rate is often the strongest reason to consider keeping that loan and using a HELOC.
Next, decide whether payment certainty or borrowing flexibility matters more. A fixed-rate cash-out refinance can make budgeting easier. A HELOC can prevent you from paying interest on money sitting unused, but it can bring variable-rate risk and a second monthly payment.
Finally, be honest about the repayment plan. Using equity to improve a home, eliminate high-interest debt with disciplined budgeting, or solve a necessary financial need can be strategic. Using it repeatedly to cover an ongoing monthly shortfall deserves a closer look at the full budget.
For homeowners in Virginia, North Carolina, and Florida, a side-by-side review can show whether a cash-out refinance, a HELOC, or leaving the current mortgage alone produces the strongest result. Phillip Ferguson can compare structures across a broad lender network without forcing your situation into one bank’s menu.
Your equity has taken years to build. Use it with a plan that protects the mortgage you already have while giving your next goal a realistic path forward.
 Hi, my name is Phillip Ferguson. I’m a Loan Officer with NEXA Lending LLC., offering personalized mortgage solutions, fast customized quotes, great rates and service with integrity.
A buyer finds a home they love on Friday, then worries that getting qualified with a lender will lower their credit score before they can even write an offer. It is a fair concern. Does prequalification affect credit score? Usually, no – not when the lender uses a soft credit inquiry for an initial mortgage review. But the answer depends on what the lender calls “prequalification” and how they pull your credit.
That distinction matters when you are comparing rates, preparing to buy in Hampton Roads, or looking at a refinance, cash-out loan, or investment property financing. You should be able to understand your financing position without accidentally taking a credit hit for every conversation.
Does Prequalification Affect Credit Score?
In most cases, mortgage prequalification does not affect your credit score because it relies on information you provide and may include a soft credit pull. A soft inquiry allows a lender to review parts of your credit profile without creating the type of inquiry that impacts your FICO score.
A true initial prequalification is often a starting-point estimate. You may share your income, monthly debts, assets, estimated down payment, and permission for a soft credit review. The lender then uses that information to discuss a likely price range, loan options, and possible next steps.
A hard inquiry is different. It generally occurs when you move into a formal mortgage application or a more fully documented preapproval process. Hard inquiries can have a small, temporary effect on your score, although mortgage credit-shopping rules often limit the impact when you apply with multiple lenders in a focused window.
The practical takeaway is simple: ask before authorizing any credit pull. A lender should be able to tell you clearly whether the review is a soft inquiry or a hard inquiry.
Soft Pulls vs. Hard Pulls for a Mortgage
The terminology can feel confusing because lenders do not all use the same labels. One company’s “prequalification” may be another company’s “preapproval.” What counts is the credit process behind the label.
A soft inquiry is designed for early planning
Soft inquiries are commonly used when you want an initial look at your buying power without a score impact. You may also see soft inquiries when you check your own credit, receive certain pre-screened offers, or work with a lender on an early scenario review.
Soft pulls do not show to other lenders as an application for new credit. They are not factored into standard FICO scoring in the same way hard inquiries are. That makes them useful if you are six months from buying, uncertain whether to refinance, or comparing how different down payments could affect your payment.
Still, a soft pull is not the same as final approval. Your loan program, rate, purchase price, and approval conditions can change after a full application, documentation review, appraisal, and underwriting.
A hard inquiry supports a formal application
A hard credit inquiry is typically used when you submit a mortgage application and request a lender’s formal review. It gives the lender the detailed credit information needed to evaluate your loan more thoroughly.
For many consumers, one hard inquiry has a modest effect, often only a few points. The impact varies based on the rest of your profile. Someone with a long credit history and few recent applications may see little change. Someone rebuilding credit, carrying high balances, or applying for several types of new credit at once may see a more noticeable effect.
The inquiry itself is rarely the main issue in a mortgage approval. Late payments, high revolving balances, collection accounts, recent new debt, and changes to your income or employment can matter far more.
Why Mortgage Rate Shopping Usually Does Not Create Multiple Hits
You should compare mortgage options. Rates, lender credits, terms, and loan structures can vary significantly, especially when you are deciding between conventional, FHA, VA, jumbo, adjustable-rate, or DSCR financing.
Credit scoring models generally recognize that consumers shop for mortgage financing. Multiple mortgage-related hard inquiries made within a shopping period are commonly treated as one inquiry for scoring purposes. The exact window depends on the scoring model, but it is generally between 14 and 45 days.
That does not mean you should spread mortgage applications across several months without a plan. Once you are ready for formal quotes and preapproval, concentrate your comparisons into a short period. Keep notes on the rate, annual percentage rate, points, lender credits, estimated cash to close, lock period, and loan term. The lowest advertised rate is not automatically the lowest-cost mortgage.
Working with a mortgage professional who can compare multiple lender options can also reduce unnecessary applications. Instead of completing separate applications at several retail banks, you may be able to review competitive structures through one organized process. Phillip Ferguson at NEXA Lending can begin with a non-credit-impacting scenario review, then help determine when a full application makes sense.
Prequalification, Preapproval, and Approval Are Not the Same
A prequalification helps you estimate what could be possible. A preapproval is usually a stronger signal to a seller because it often involves a credit review and documentation such as pay stubs, W-2s, tax returns, bank statements, and identification. Neither is a final loan approval.
Final approval happens only after the lender reviews the complete file. For a purchase, that usually includes the property appraisal, title work, insurance, contract details, and underwriting conditions. For a refinance, the lender also evaluates the existing mortgage, property value, payoff figures, and the purpose of the new loan.
This is why buyers should avoid treating a prequalification letter as permission to stretch their budget. A comfortable mortgage payment should account for principal, interest, taxes, homeowners insurance, association dues if applicable, maintenance, and the realities of your monthly cash flow.
How to Protect Your Credit While Preparing for a Home Loan
The weeks before and during a mortgage application are not the time for major credit moves. You do not need perfect credit to buy or refinance, but you do need consistency.
Keep credit card balances low relative to their limits, and make every payment on time. Avoid opening a new card, financing furniture, leasing a car, or co-signing for someone else unless you have discussed it with your loan originator first. A new monthly payment can change your debt-to-income ratio even if your credit score remains strong.
Do not close long-standing credit cards simply because they have a zero balance. Closing an account can reduce available revolving credit and potentially increase your utilization ratio. If you notice an error on your report, address it early. Dispute timelines can be unpredictable, so waiting until you are under contract can add pressure to an already fast-moving transaction.
If you have already had a hard inquiry, do not panic. Focus on the factors you can control: pay on time, avoid new debt, maintain your cash reserves, and provide requested documents promptly. A lender can help you understand whether a specific issue changes your available loan options.
Questions to Ask Before You Get Qualified
Before you submit information, ask whether the lender will use a soft or hard credit inquiry. Ask what documentation is needed, how long the qualification is expected to remain valid, and whether the estimate includes property taxes, insurance, mortgage insurance, and any homeowner association dues.
If you are comparing lenders, ask for more than a rate. Find out about points, lender fees, underwriting timelines, lock options, prepayment penalties where applicable, and the estimated funds required to close. A loan that looks cheaper at first can cost more if its fees or structure do not fit your plans.
For a refinance, ask how long it will take to recover closing costs through the expected monthly savings. For a cash-out refinance or home-equity option, ask how the new payment and loan balance affect your longer-term goals. For investors, ask how rental income, reserves, and property type affect qualification.
The Best Time to Start
Start early enough to make smart decisions, not just fast ones. A soft-pull prequalification can give you a useful baseline before you call a real estate agent, tour homes, or decide whether a refinance is worthwhile. Then, when you are ready to make an offer or lock financing, you can move into the formal application process with fewer surprises.
Your credit score is one part of the mortgage picture, not a reason to delay getting answers. Get clear on the type of credit review being used, compare the full cost of your options, and make your next move with a payment and loan structure that supports the life you are building.
A buyer finds a home they love on Friday, then worries that getting qualified with a lender will lower their credit score before they can even write an offer. It is a fair concern. Does prequalification affect credit score? Usually, no – not when the lender uses a soft credit inquiry for an initial mortgage review. But the answer depends on what the lender calls “prequalification” and how they pull your credit.
That distinction matters when you are comparing rates, preparing to buy in Hampton Roads, or looking at a refinance, cash-out loan, or investment property financing. You should be able to understand your financing position without accidentally taking a credit hit for every conversation.
Does Prequalification Affect Credit Score?
In most cases, mortgage prequalification does not affect your credit score because it relies on information you provide and may include a soft credit pull. A soft inquiry allows a lender to review parts of your credit profile without creating the type of inquiry that impacts your FICO score.
A true initial prequalification is often a starting-point estimate. You may share your income, monthly debts, assets, estimated down payment, and permission for a soft credit review. The lender then uses that information to discuss a likely price range, loan options, and possible next steps.
A hard inquiry is different. It generally occurs when you move into a formal mortgage application or a more fully documented preapproval process. Hard inquiries can have a small, temporary effect on your score, although mortgage credit-shopping rules often limit the impact when you apply with multiple lenders in a focused window.
The practical takeaway is simple: ask before authorizing any credit pull. A lender should be able to tell you clearly whether the review is a soft inquiry or a hard inquiry.
Soft Pulls vs. Hard Pulls for a Mortgage
The terminology can feel confusing because lenders do not all use the same labels. One company’s “prequalification” may be another company’s “preapproval.” What counts is the credit process behind the label.
A soft inquiry is designed for early planning
Soft inquiries are commonly used when you want an initial look at your buying power without a score impact. You may also see soft inquiries when you check your own credit, receive certain pre-screened offers, or work with a lender on an early scenario review.
Soft pulls do not show to other lenders as an application for new credit. They are not factored into standard FICO scoring in the same way hard inquiries are. That makes them useful if you are six months from buying, uncertain whether to refinance, or comparing how different down payments could affect your payment.
Still, a soft pull is not the same as final approval. Your loan program, rate, purchase price, and approval conditions can change after a full application, documentation review, appraisal, and underwriting.
A hard inquiry supports a formal application
A hard credit inquiry is typically used when you submit a mortgage application and request a lender’s formal review. It gives the lender the detailed credit information needed to evaluate your loan more thoroughly.
For many consumers, one hard inquiry has a modest effect, often only a few points. The impact varies based on the rest of your profile. Someone with a long credit history and few recent applications may see little change. Someone rebuilding credit, carrying high balances, or applying for several types of new credit at once may see a more noticeable effect.
The inquiry itself is rarely the main issue in a mortgage approval. Late payments, high revolving balances, collection accounts, recent new debt, and changes to your income or employment can matter far more.
Why Mortgage Rate Shopping Usually Does Not Create Multiple Hits
You should compare mortgage options. Rates, lender credits, terms, and loan structures can vary significantly, especially when you are deciding between conventional, FHA, VA, jumbo, adjustable-rate, or DSCR financing.
Credit scoring models generally recognize that consumers shop for mortgage financing. Multiple mortgage-related hard inquiries made within a shopping period are commonly treated as one inquiry for scoring purposes. The exact window depends on the scoring model, but it is generally between 14 and 45 days.
That does not mean you should spread mortgage applications across several months without a plan. Once you are ready for formal quotes and preapproval, concentrate your comparisons into a short period. Keep notes on the rate, annual percentage rate, points, lender credits, estimated cash to close, lock period, and loan term. The lowest advertised rate is not automatically the lowest-cost mortgage.
Working with a mortgage professional who can compare multiple lender options can also reduce unnecessary applications. Instead of completing separate applications at several retail banks, you may be able to review competitive structures through one organized process. Phillip Ferguson at NEXA Lending can begin with a non-credit-impacting scenario review, then help determine when a full application makes sense.
Prequalification, Preapproval, and Approval Are Not the Same
A prequalification helps you estimate what could be possible. A preapproval is usually a stronger signal to a seller because it often involves a credit review and documentation such as pay stubs, W-2s, tax returns, bank statements, and identification. Neither is a final loan approval.
Final approval happens only after the lender reviews the complete file. For a purchase, that usually includes the property appraisal, title work, insurance, contract details, and underwriting conditions. For a refinance, the lender also evaluates the existing mortgage, property value, payoff figures, and the purpose of the new loan.
This is why buyers should avoid treating a prequalification letter as permission to stretch their budget. A comfortable mortgage payment should account for principal, interest, taxes, homeowners insurance, association dues if applicable, maintenance, and the realities of your monthly cash flow.
How to Protect Your Credit While Preparing for a Home Loan
The weeks before and during a mortgage application are not the time for major credit moves. You do not need perfect credit to buy or refinance, but you do need consistency.
Keep credit card balances low relative to their limits, and make every payment on time. Avoid opening a new card, financing furniture, leasing a car, or co-signing for someone else unless you have discussed it with your loan originator first. A new monthly payment can change your debt-to-income ratio even if your credit score remains strong.
Do not close long-standing credit cards simply because they have a zero balance. Closing an account can reduce available revolving credit and potentially increase your utilization ratio. If you notice an error on your report, address it early. Dispute timelines can be unpredictable, so waiting until you are under contract can add pressure to an already fast-moving transaction.
If you have already had a hard inquiry, do not panic. Focus on the factors you can control: pay on time, avoid new debt, maintain your cash reserves, and provide requested documents promptly. A lender can help you understand whether a specific issue changes your available loan options.
Questions to Ask Before You Get Qualified
Before you submit information, ask whether the lender will use a soft or hard credit inquiry. Ask what documentation is needed, how long the qualification is expected to remain valid, and whether the estimate includes property taxes, insurance, mortgage insurance, and any homeowner association dues.
If you are comparing lenders, ask for more than a rate. Find out about points, lender fees, underwriting timelines, lock options, prepayment penalties where applicable, and the estimated funds required to close. A loan that looks cheaper at first can cost more if its fees or structure do not fit your plans.
For a refinance, ask how long it will take to recover closing costs through the expected monthly savings. For a cash-out refinance or home-equity option, ask how the new payment and loan balance affect your longer-term goals. For investors, ask how rental income, reserves, and property type affect qualification.
The Best Time to Start
Start early enough to make smart decisions, not just fast ones. A soft-pull prequalification can give you a useful baseline before you call a real estate agent, tour homes, or decide whether a refinance is worthwhile. Then, when you are ready to make an offer or lock financing, you can move into the formal application process with fewer surprises.
Your credit score is one part of the mortgage picture, not a reason to delay getting answers. Get clear on the type of credit review being used, compare the full cost of your options, and make your next move with a payment and loan structure that supports the life you are building.
 Hi, my name is Phillip Ferguson. I’m a Loan Officer with NEXA Lending LLC., offering personalized mortgage solutions, fast customized quotes, great rates and service with integrity.
 Hi, my name is Phillip Ferguson. I’m a Loan Officer with NEXA Lending LLC., offering personalized mortgage solutions, fast customized quotes, great rates and service with integrity.
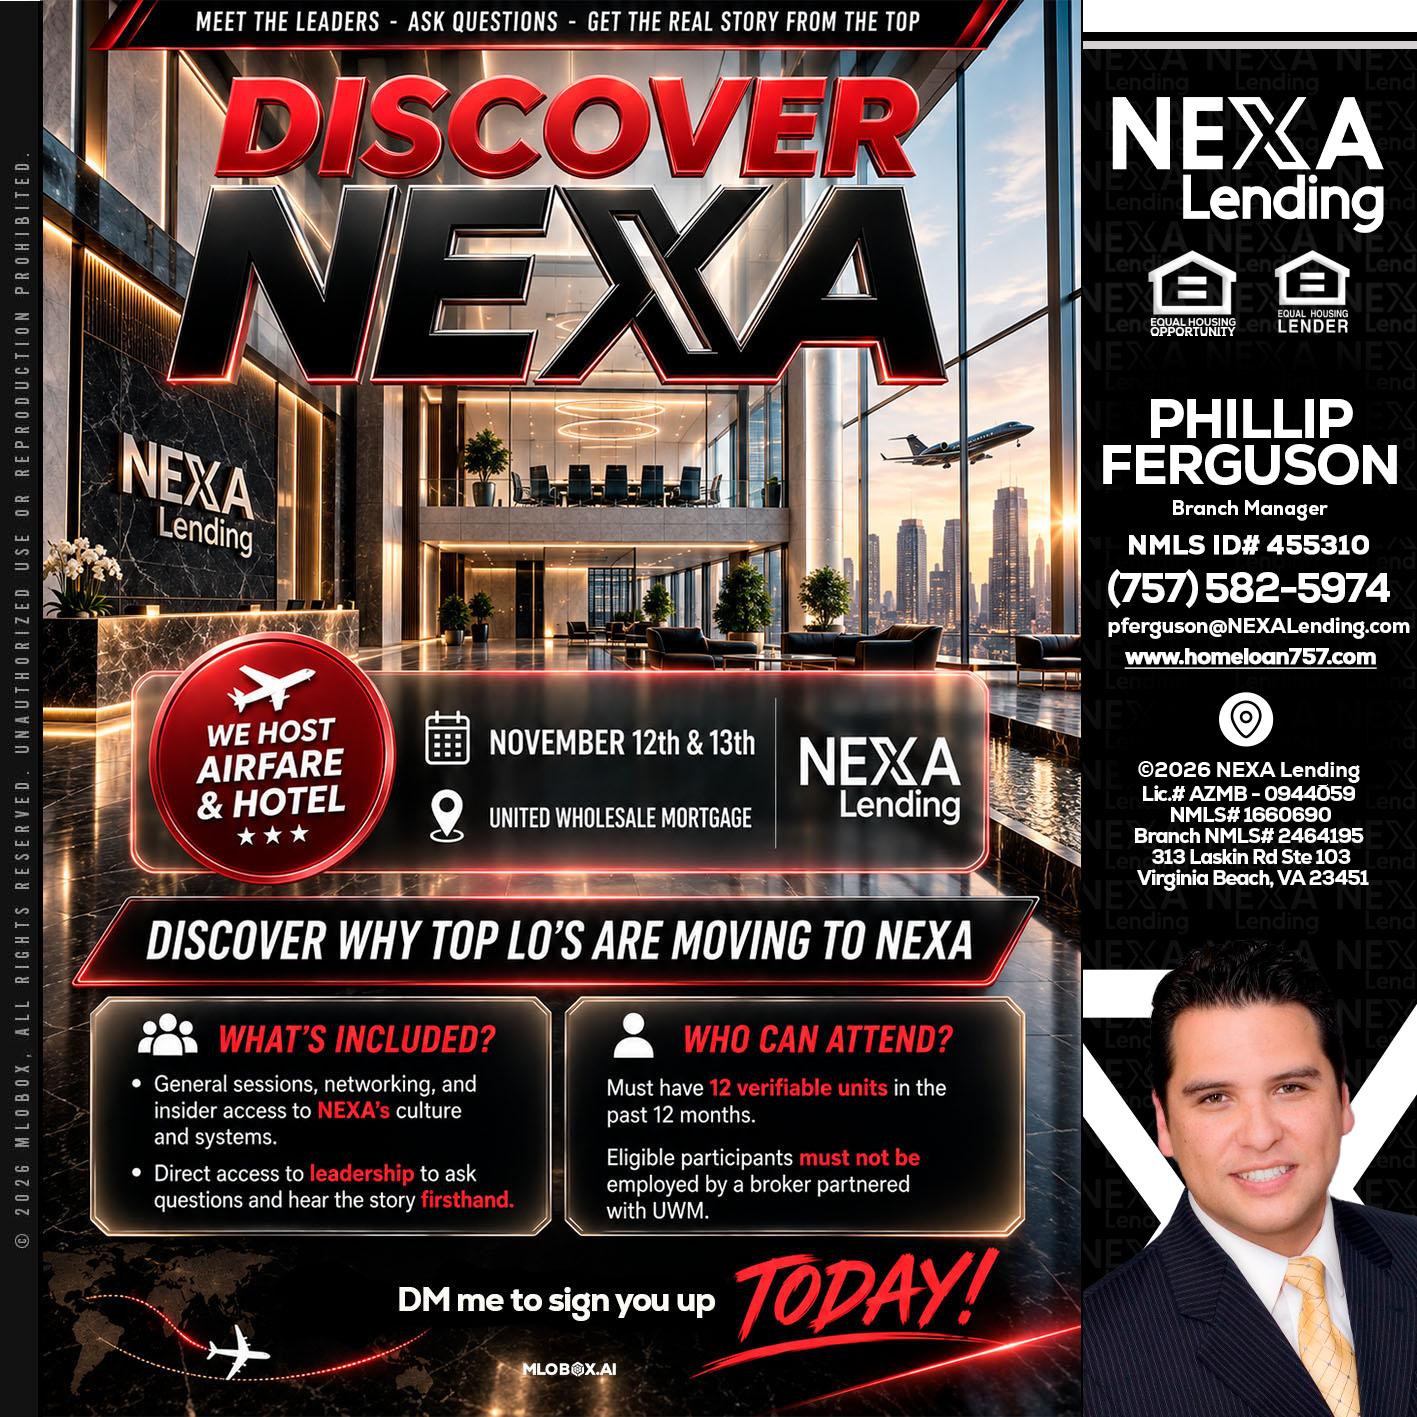 Hi, my name is Phillip Ferguson. I’m a Loan Officer with NEXA Lending LLC., offering personalized mortgage solutions, fast customized quotes, great rates and service with integrity.
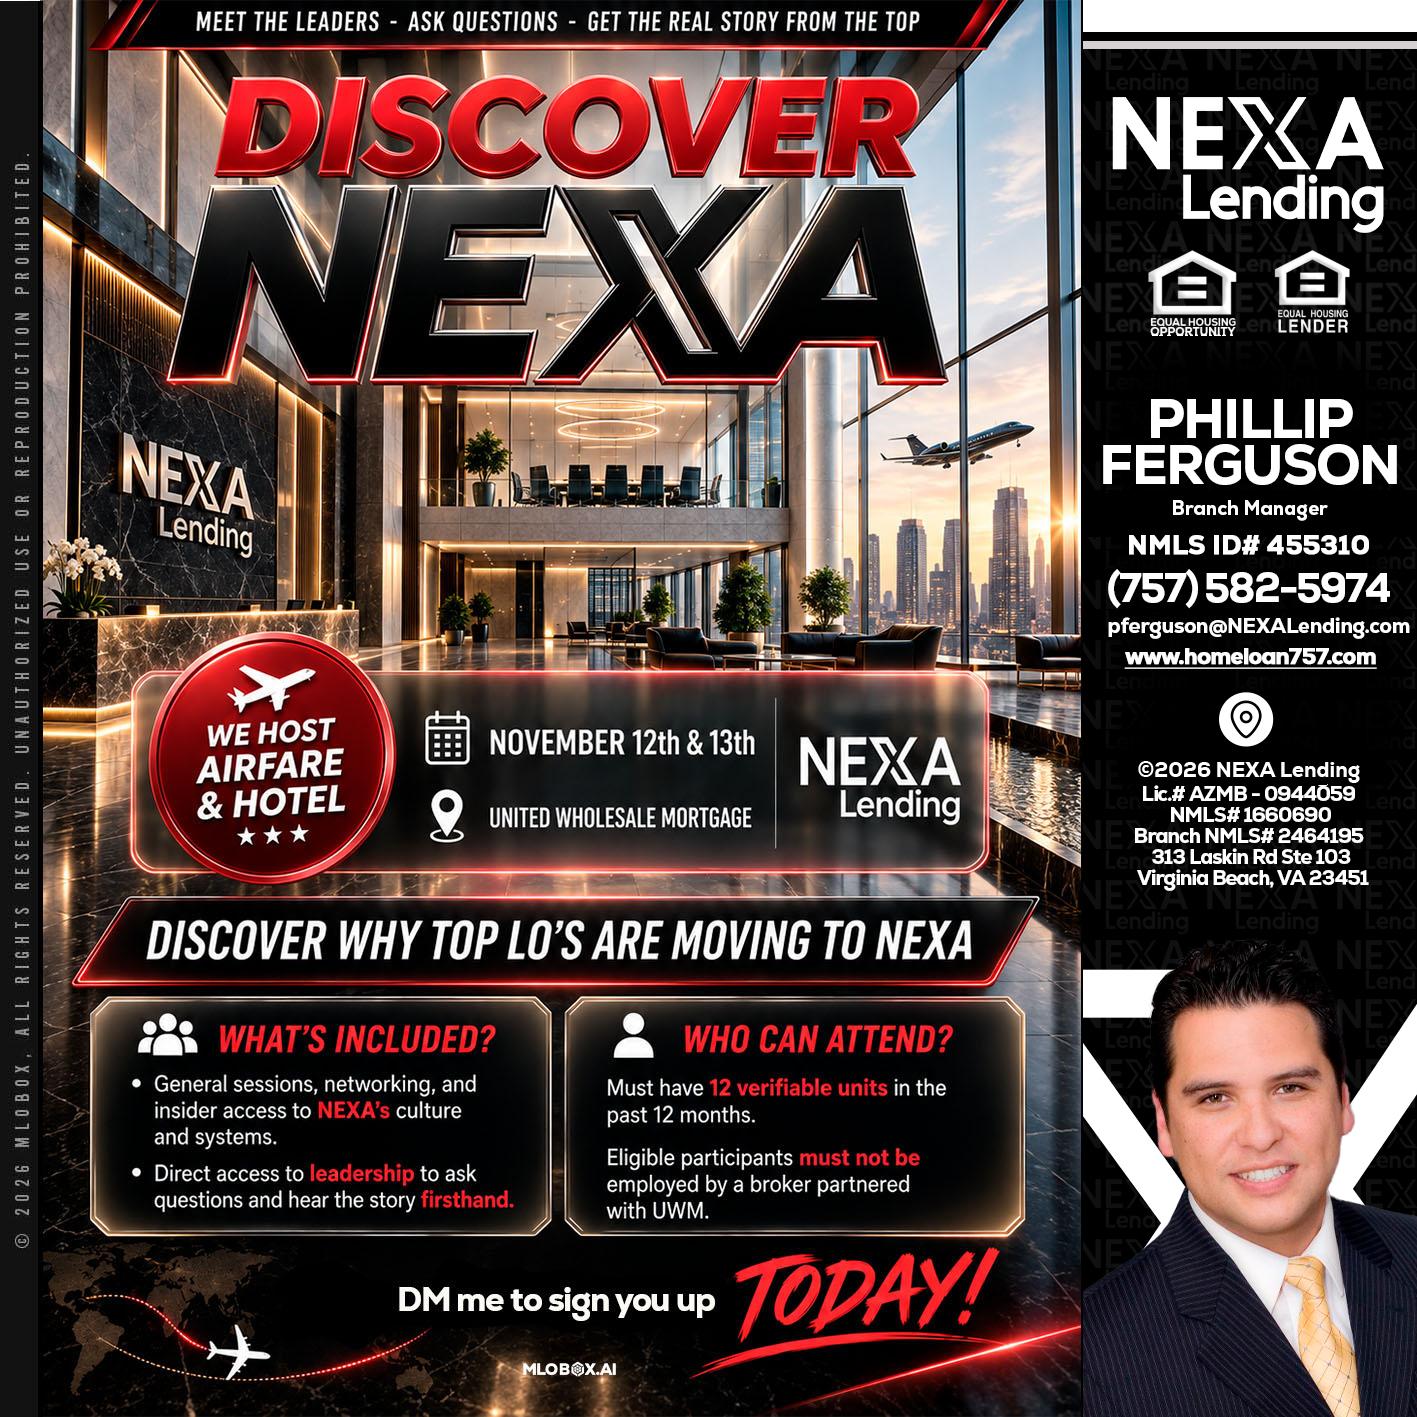 Hi, my name is Phillip Ferguson. I’m a Loan Officer with NEXA Lending LLC., offering personalized mortgage solutions, fast customized quotes, great rates and service with integrity.
 Hi, my name is Phillip Ferguson. I’m a Loan Officer with NEXA Lending LLC., offering personalized mortgage solutions, fast customized quotes, great rates and service with integrity.

NEXA Lending LLC.
AZMB #0944059
An Equal Housing Lender All Rights Reserved. © 2026
Contact Us
Branch:
313 Laskin Rd Ste
103 Room 4, Virginia
Beach, VA 23451
103 Room 4, Virginia
Beach, VA 23451
Corporate:
5559 S Sossaman
Rd Building 1 #101,
Mesa, AZ 85212
Rd Building 1 #101,
Mesa, AZ 85212
Proud Supporter of


Phillip Services all of
Florida, North Carolina, Virginia